Ask ten European fashion buyers why they source from Vietnam and a good number will mention the EU-Vietnam Free Trade Agreement. Zero duty on apparel sounds like a straightforward advantage. In practice, a large share of Vietnamese garments still enter the EU paying the full duty rate, not because the agreement failed, but because the goods were never eligible in the first place.
The reason is almost always the fabric. The EVFTA rules of origin for apparel do not reward a garment simply for being cut and sewn in Vietnam. They look one step further back, at where the fabric was knitted or woven. If that step happened in the wrong country, the shirt is still “Made in Vietnam” on its label, but it does not originate in Vietnam for EU tariff purposes.
This guide explains, from the factory side, how the rule works for knitwear and wovens, where cumulation and tolerances give you room to manoeuvre, what paperwork your customs broker will need, and how to build origin into your sourcing decisions before the first sample is cut. It is written for importers, brand owners and buying offices shipping to the EU and UK. It is not legal advice: the official texts and your customs broker always have the final word, and we link to the primary sources throughout.
Table of Contents
- Why Origin, Not the Factory Address, Decides Your EU Duty
- EVFTA and Apparel: The Numbers That Matter
- The Fabric-Forward Rule Explained
- What the Rules Say for Knitwear (Chapter 61) and Wovens (Chapter 62)
- Cumulation: When EU and Korean Fabric Count as Originating
- Tolerances, Trims and Accessories: The Fine Print That Helps
- Four Real-World Sourcing Scenarios
- Proof of Origin: EUR.1, Origin Declarations and REX
- What Changes for the UK and Other Markets
- A Buyer’s Checklist Before You Place an EU Order
- Frequently Asked Questions
- Conclusion
- Plan an EU Order with AT Garment Factory
Why Origin, Not the Factory Address, Decides Your EU Duty
Customs works with two ideas of origin. Non-preferential origin decides the country-of-origin label and general trade measures; preferential origin decides whether a shipment can claim a reduced or zero rate under a trade agreement. They often match, but not always.
For a T-shirt sewn in Ho Chi Minh City from Chinese jersey, the label will normally say “Made in Vietnam”, because the garment took its final shape there. Under the EVFTA, however, that same T-shirt does not qualify for the preferential rate, because the agreement’s product-specific rule requires the fabric itself to be made in Vietnam or in the EU (with limited exceptions covered below). The importer pays the standard most-favoured-nation (MFN) duty instead.
That gap between “Made in Vietnam” and “originating in Vietnam” is where most misunderstandings start: buyers plan margins around a duty saving that was never available, and discover it only when no certificate can be issued, or when an EU verification arrives months later. If you are new to how origin labels themselves work, our guide to clothing label requirements for the US, EU and UK covers the labelling side; this article is about the duty side.
EVFTA and Apparel: The Numbers That Matter
The figures below come from official EU and Vietnamese government sources. Treat them as context, not as a forecast for your product.
- The EVFTA entered into force on 1 August 2020. According to the European Commission’s Access2Markets portal, the EU will progressively remove its duties on imports from Vietnam by 2027, while Vietnam has a longer schedule running to 2030.
- Apparel lines were not all cut to zero on day one. Each tariff line has a staging category, and interim reductions take effect on 1 January each year after the first cut in August 2020, as explained in the CCI France Vietnam EVFTA FAQ. Many apparel lines are commonly described as being on a seven-year phase-out ending in 2027 (Trade With Viet), against an MFN rate often cited at around 12% for garments. Always check the exact rate for your HS code in the EU’s TARIC database.
- Vietnam’s Ministry of Industry and Trade (MOIT) reports that textile and garment exports to the EU were estimated at about US$4.74 billion in 2025, up roughly 9.7% year on year, with the EU accounting for around 12% of the sector’s exports (MOIT, December 2025).
- In the same period, textile exports shipped with an EUR.1 certificate under the EVFTA were reported at about US$1.38 billion, and with the UK version of the EUR.1 at about US$211 million (MOIT, December 2025).
- The Vietnam Textile and Apparel Association (VITAS) has put EVFTA utilisation in the textile sector at roughly 30-35%, compared with about 15% for the CPTPP, and estimates that around 70% of the industry’s materials are still imported, close to half of them from China (VITAS via MOIT).
In short: plenty of Vietnamese apparel goes to the EU, but only a minority claims the preference, and Vietnamese officials name fabric origin as the main barrier. The duty saving is not something you get by choosing Vietnam. It is something you design into the product.
The Fabric-Forward Rule Explained
Officially, the EVFTA sets out its origin rules in Protocol 1 and the list of required working or processing in its Annex II. In Vietnam, the rules are implemented by Circular 11/2020/TT-BCT. For most garments, the rule is commonly summarised as “double transformation” or “fabric forward”.
Two transformations, both in the right place
A garment qualifies when two key stages happen in Vietnam or the EU: first, the fabric is formed (knitted or woven), and second, the garment is made up from it, which includes cutting and sewing. Vietnam’s investment promotion agency describes it plainly: fabric and the cut-and-sew process must be done in Vietnam or the EU, so the fabric has to obtain Vietnamese or EU origin (Invest Vietnam). MOIT puts it even more directly: a Vietnamese company cannot import fabric from China, sew it into garments and claim EVFTA preferences when exporting to the EU (MOIT).
What the rule does not require
The fabric-forward rule is less strict than the yarn-forward rule used in some other agreements. The yarn itself does not have to be Vietnamese. A Vietnamese mill can knit imported cotton yarn into jersey, and a Vietnamese factory can cut and sew that jersey into a T-shirt that qualifies. That distinction matters, because Vietnam’s spinning and knitting capacity is more developed than its weaving, dyeing and finishing capacity in some fabric categories.
Why buyers get caught out
Most origin problems come from three habits: choosing fabric on price and handfeel without asking where the mill is; approving a late fabric substitution, such as an imported fleece because the local option missed a colour; and assuming the factory will handle origin. A good factory will flag the issue, but the decision to pay for originating fabric belongs to the buyer. This is why we recommend raising origin at the tech pack and sample development stage, not after the price is agreed.
What the Rules Say for Knitwear (Chapter 61) and Wovens (Chapter 62)
Garments are split across two chapters of the Harmonized System. Which one your product falls into decides the exact wording of the rule. The summary below paraphrases the product-specific rules as published in Vietnam’s implementing circular; the official text contains footnotes and exceptions that your broker should check for each HS line.
Chapter 61: knitted or crocheted apparel
T-shirts, polos, hoodies, sweatshirts, leggings, most activewear and jersey dresses usually sit in Chapter 61. For garments sewn together from two or more pieces of knitted fabric, the rule is knitting and making-up, including cutting. In other words, the knitted fabric must be knitted in Vietnam or the EU (or qualify through cumulation), and the garment must be cut and sewn in Vietnam.
For garments knitted to shape, such as fully fashioned sweaters, the rule moves one step back, to spinning fibres or dyeing natural-fibre yarn accompanied by knitting. That is a stricter test, so check it carefully if you are developing knitwear rather than cut-and-sew jersey.
Chapter 62: woven apparel
Shirts, trousers, jeans, chinos, woven dresses, jackets and most uniforms sit in Chapter 62. The general rule is weaving accompanied by making-up, including cutting. The shell fabric must be woven in Vietnam or the EU (or qualify through cumulation). For certain embroidered women’s, girls’ and baby garments, there is an alternative that allows unembroidered fabric as long as its value does not exceed 40% of the ex-works price of the product (Circular 11/2020/TT-BCT, Annex II). Similar value-based alternatives exist for a few specific items such as some scarves and shawls.
Why classification comes first
Because the rule depends on the chapter and heading, the first job is to classify the garment correctly. A cotton-spandex top can be knit or woven depending on the fabric construction, and a jacket with a knitted body and woven panels can raise classification questions. Agree the HS code with your customs broker before you finalise fabric, not after. If you are weighing fabrics for a hoodie programme, our comparison of French terry versus fleece explains the construction differences that also affect sourcing options.
Cumulation: When EU and Korean Fabric Count as Originating
Cumulation is the mechanism that lets materials from a partner country count as if they originated in Vietnam. The EVFTA has two forms that matter for apparel.
Bilateral cumulation with the EU
Materials originating in the EU can be used in Vietnamese products without affecting their originating status. A Vietnamese factory can therefore sew Italian or Portuguese fabric into garments for the EU and still claim the preference, provided the fabric itself is of EU origin and documented as such. This helps for premium shirting, wool blends and technical fabrics not widely made in Vietnam, though fabric freight and lead time must be planned.
Korean fabric for Chapters 61 and 62
The more commercially important provision is sectoral cumulation with South Korea, a country that has free trade agreements with both the EU and Vietnam. Under this provision, fabric originating in Korea can be used to make Chapter 61 and 62 garments in Vietnam, and those garments can still be treated as originating, as long as the manufacturing in Vietnam goes beyond the “insufficient operations” listed in the protocol (CCI France Vietnam cumulation guide; Invest Vietnam). According to the CCIFV guide, proofs of origin issued under this rule carry a specific entry referring to Article 3(7) of Protocol 1.
Other partner countries
The agreement allows this sectoral cumulation to be extended to fabric from other countries with which both the EU and Vietnam apply preferential trade agreements. Some Vietnamese government sources mention Japan, and in some articles Canada, in this context (MOIT), while the CCIFV guide describes the extension as something that applies on request. Because the status of these extensions can change, confirm with your broker or the EU’s Access2Markets helpdesk before relying on any partner other than the EU and Korea.
Cumulation does not cover China, Taiwan, Hong Kong or ASEAN neighbours for apparel. Fabric from those sources makes the garment non-originating under the EVFTA, however much work is done on it in Vietnam.
Tolerances, Trims and Accessories: The Fine Print That Helps
The headline rule is strict, but the protocol contains tolerances that matter in day-to-day production. These come from the introductory notes to the list of required working or processing (EVFTA Protocol 1, Annex I). They are technical, so treat this as orientation rather than a definitive reading.
Buttons, zips and other non-textile components
Note 7.2 states that materials not classified within Chapters 50 to 63 may be used freely in textile products. The official example is trousers: the rule does not prevent the use of metal buttons or slide fasteners, even though zips normally contain textile tape. In practical terms, imported buttons, snaps, rivets and zippers do not usually break origin. (Note 7.3 adds that where a percentage-based rule applies, their value still counts in the calculation.)
Other textile materials up to 8% of value
Note 7.1 allows textile materials that do not satisfy the rule to be used, where the list refers to this note, provided they are classified in a heading other than that of the product and their value does not exceed 8% of the ex-works price. This is the kind of provision that can cover items such as labels, small lining components or tapes, but whether a specific component qualifies depends on its classification and value, so it should be checked case by case.
Mixed fabrics: the 10% and 20% weight tolerances
Note 6 deals with products made from a mixture of basic textile materials. Where it applies, non-originating basic textile materials that together make up 10% or less of the total weight of all basic textile materials can be disregarded, but only in products made from two or more basic textile materials. For products incorporating polyurethane yarn with flexible polyether segments, which is how elastane or spandex is described, the tolerance is 20% in respect of that yarn. For activewear and stretch denim, that can be relevant, but again, a broker should confirm the calculation for your specific construction.
What the tolerances will not do
None of these provisions rescues a garment whose main shell fabric is non-originating. They are designed for small components and blends, not for the bulk of the product. If your body fabric comes from a non-eligible mill, the tolerances will not save the preference.
Four Real-World Sourcing Scenarios
These simplified examples illustrate the logic. They are not rulings; real outcomes depend on classification and documentation.
Scenario 1: Cotton T-shirt from Vietnamese-knitted jersey
A brand orders a 180 GSM cotton T-shirt. The yarn is imported, but the jersey is knitted and dyed at a mill in Vietnam, and the factory cuts and sews it. The fabric-forward rule is met: knitting and making-up both happen in Vietnam. With a valid EUR.1, the importer should be able to claim the EVFTA rate for that HS line. Our T-shirt GSM guide covers how fabric weight choices also affect cost.
Scenario 2: Fleece hoodie from imported Chinese fleece
A brushed fleece in a specific heather colour is only available from a mill in China at the right price. The hoodie is cut, sewn and printed in Vietnam. The label correctly says “Made in Vietnam”, but the garment does not meet the EVFTA rule, so the importer pays the MFN duty. The options are to accept the duty, find an originating fleece in Vietnam, Korea or the EU, or adjust the colour to match what an eligible mill can supply.
Scenario 3: Polo shirt in Korean piqué
A polo programme uses a piqué knitted in Korea. Under the sectoral cumulation provision, the Korean fabric can be treated as originating for a Chapter 61 garment made in Vietnam, provided the fabric’s Korean origin is documented. This route is often how Vietnamese factories serve EU buyers who need specific performance or premium knits.
Scenario 4: Woven jacket with mixed fabric sources
A jacket uses a non-originating shell fabric with a Vietnamese-woven lining and imported zips. The zips are not a problem, and the lining is originating, but the shell is the main fabric and it fails the rule. The jacket does not qualify. Reversing the sources, with an originating shell and an imported lining, may change the result if the lining stays within the applicable tolerance, which is exactly the kind of question to put to a broker before ordering.
Origin therefore belongs next to price and quality in the fabric decision. Fabric is already the largest line on the cost sheet, as our garment cost breakdown guide explains, so compare the landed cost of an originating fabric against a cheaper one that carries full EU duty.
Proof of Origin: EUR.1, Origin Declarations and REX
Meeting the rule is one thing. Proving it at the EU border is another. Several sourcing guides online still describe a self-certification route for Vietnamese exporters, so it is worth being precise about what the official EU sources say.
Movement certificate EUR.1
For goods originating in Vietnam, the standard proof is the movement certificate EUR.1. The EU’s own EVFTA guidance identifies Vietnam’s Ministry of Industry and Trade as the issuing body. The exporter applies electronically with supporting documents, and the certificate is then printed, stamped and signed on paper. According to Access2Markets, a certificate should be issued as soon as possible and no later than three working days after the date of export, and it can be issued retrospectively in specific situations, such as errors or omissions at the time of export.
Since May 2025, MOIT has also centralised the issuance of other certificates of origin that were previously delegated to the Vietnam Chamber of Commerce and Industry (VCCI), such as Form A and non-preferential certificates (Viet Nam News). For the EVFTA, the EUR.1 was already a MOIT document, so the practical effect for EU buyers is mostly that all origin paperwork now runs through one authority.
Origin declaration for small consignments
For consignments with a total value not exceeding €6,000, any Vietnamese exporter can make out an origin declaration on the invoice or another commercial document instead of obtaining a EUR.1 (EU guidance). This is useful for samples, sales samples and small test orders, which are common when brands start with low quantities. If you are planning a first order at smaller volumes, our article on low MOQ manufacturing in Vietnam explains how order tiers work.
What about REX?
The EU’s REX system lets registered exporters self-certify origin under several EU agreements. For goods exported from Vietnam under the EVFTA, Access2Markets states that an origin declaration by an approved or registered Vietnamese exporter will only become available after Vietnam has notified such a system to the EU, and that this is not yet the case at the time of writing. If a supplier offers a REX statement in place of a EUR.1 for a large EVFTA shipment, ask your broker to confirm it will be accepted before the goods leave. A statement on origin, where it is used, is valid for 12 months from the date it was made out.
What the exporter must be able to show
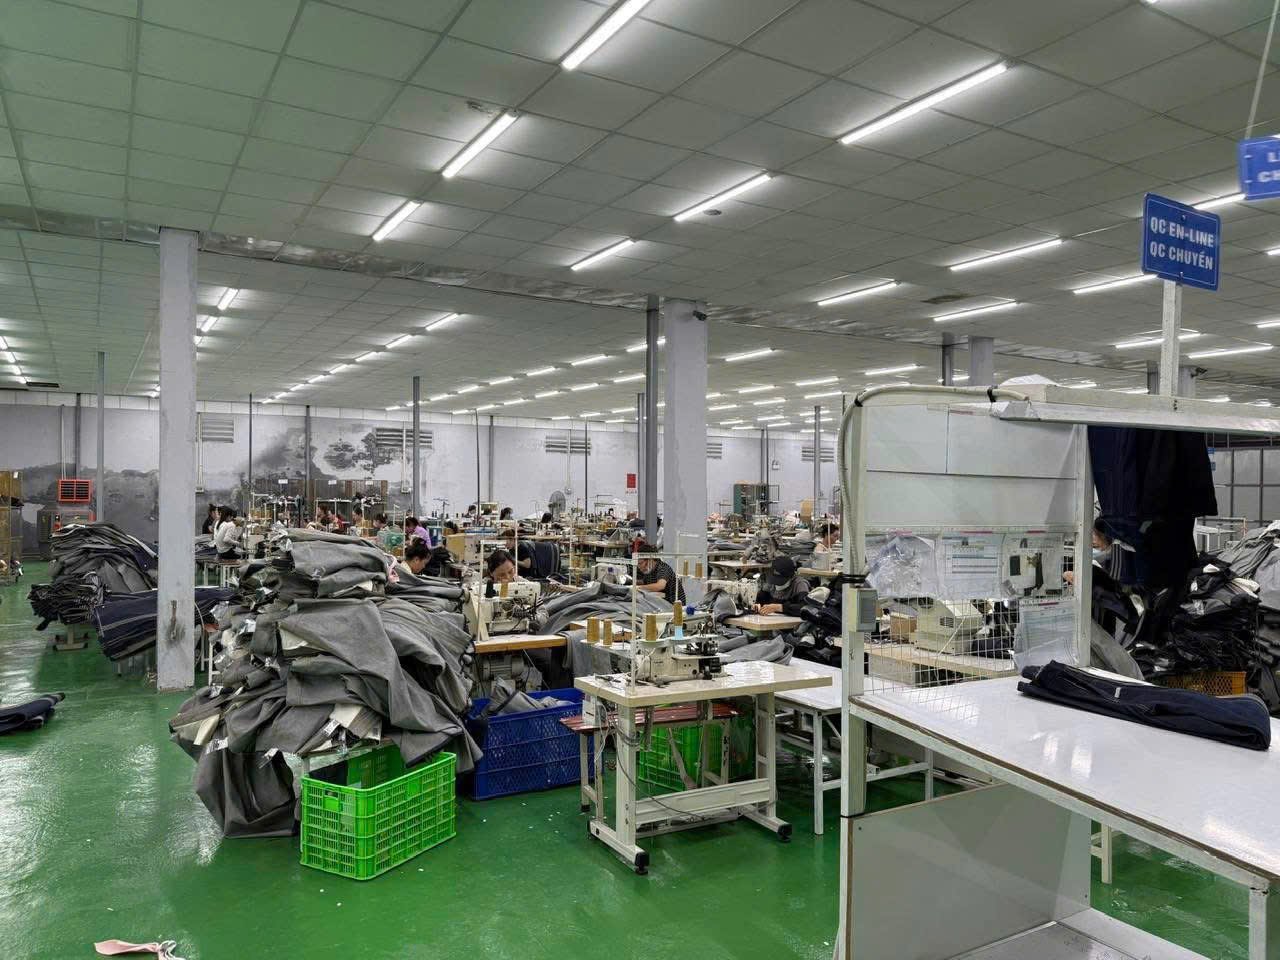
A certificate is only as good as the file behind it. EU customs can verify origin after import, and if the claim fails, the importer is the one who pays the duty difference. The exporter’s file should normally include the fabric supplier’s documents proving the fabric was knitted or woven in Vietnam, or Korean or EU origin documents for cumulated fabric; purchase invoices and delivery records; production records linking that fabric to the shipped styles; and the export customs declaration. When you agree Incoterms with your factory, agree in writing who prepares and pays for the EUR.1 as well.
What Changes for the UK and Other Markets
United Kingdom: UKVFTA
After Brexit, the UK and Vietnam signed the UK-Vietnam Free Trade Agreement, which largely rolls over the EVFTA framework. Its Protocol 1 on rules of origin follows the same structure, and apparel generally faces the same two-stage, fabric-forward logic. The UK version of the EUR.1 is already in wide use: MOIT data put textile exports under the UK EUR.1 at about US$211 million in 2025 (MOIT). The UK agreement also contains provisions on cumulation with EU materials, but do not assume every EVFTA cumulation applies in identical form; check the UK annexes for your HS line.
CPTPP: yarn forward is stricter
Buyers shipping to Canada, Japan, Australia or Mexico under the CPTPP face a stricter rule. MOIT notes that the CPTPP generally requires three stages, yarn, fabric and cut-and-sew, whereas the EVFTA and UKVFTA require two (MOIT). The same fabric that qualifies for the EU may not qualify for Canada if the yarn was imported. Multi-market brands should keep separate origin assessments per destination.
United States
The US does not have a free trade agreement with Vietnam, so there is no preferential origin claim to make for US imports of Vietnamese apparel. Non-preferential origin, labelling and any additional trade measures still apply, and they have been changing frequently. If the US is your main market, check current duty treatment with a licensed customs broker.
European buyers comparing Vietnam with Turkey, which trades with the EU under a customs union rather than an FTA, will find the duty and paperwork differences in our Vietnam versus Turkey sourcing comparison.
A Buyer’s Checklist Before You Place an EU Order
This is the sequence we suggest to buyers shipping to the EU or UK.
- Classify the product. Agree the HS code with your customs broker and confirm the MFN and EVFTA rates in TARIC for your shipping year.
- Decide whether the preference matters. For a high-value, high-volume line, the saving can justify a more expensive originating fabric. For a small test order, it may not.
- Ask about fabric origin at the quotation stage. Request the mill and country of every main fabric in the bill of materials, and ask the factory to state which styles can be supplied with an EUR.1.
- Lock the fabric source in the tech pack. Record the approved mill or origin next to composition and GSM, and require written approval for any substitution.
- Check cumulation documents early. If you rely on Korean or EU fabric, make sure the supplier can provide the origin documentation the Vietnamese exporter needs.
- Review blends and small components. For stretch fabrics, contrast panels, labels and linings, ask your broker whether the tolerances apply.
- Agree the paperwork in the contract. State who applies for the EUR.1, by when, and who bears the cost if a certificate is rejected because of exporter error.
- Keep records. Importers should keep origin proofs and the supporting correspondence for the period required by EU customs rules, because verification can happen after the goods are sold.
- Re-check every season. A fabric that was originating last season may come from a different mill this season. Origin is a property of each order, not of the supplier.
Buying offices may want to make this a standard field in every purchase order. Our guide for buying offices and sourcing agents covers how to structure supplier communication more generally, and our step-by-step ordering guide shows where each decision fits in the production timeline.
Frequently Asked Questions
What are the EVFTA rules of origin for apparel?
For most garments, the EVFTA uses a fabric-forward, or double transformation, rule. The fabric must be knitted or woven in Vietnam or the EU, or come from an eligible cumulation partner such as South Korea, and the garment must then be cut and sewn in Vietnam. Cutting and sewing imported non-originating fabric is generally not enough.
Can garments made from Chinese fabric get 0% EU duty under the EVFTA?
Generally no. Fabric from China is not covered by EVFTA cumulation for apparel, so a garment sewn in Vietnam from Chinese shell fabric does not qualify for the preferential rate, even though it may legitimately carry a Made in Vietnam label. The importer pays the standard MFN duty unless another preference applies.
Does Korean fabric qualify under the EVFTA?
Yes, in principle. The agreement allows fabric originating in South Korea to be used for Chapter 61 and 62 garments made in Vietnam, provided the manufacturing in Vietnam goes beyond insufficient operations and the Korean origin of the fabric is properly documented.
Which document do I need to claim EVFTA preference in the EU?
For most commercial shipments, a movement certificate EUR.1 issued by Vietnam’s Ministry of Industry and Trade. For consignments not exceeding €6,000, the exporter can instead make out an origin declaration on the invoice. Vietnam has not yet notified a registered-exporter self-certification system to the EU, according to Access2Markets.
Do imported buttons and zippers affect EVFTA origin?
Usually not. The protocol states that materials outside Chapters 50 to 63, such as metal buttons and slide fasteners, can be used freely in textile products. Other textile components, such as labels or linings, may fall under value or weight tolerances, which should be confirmed for each style.
Is the EVFTA duty on Vietnamese clothing already zero?
Not for every line. EU duties on Vietnamese goods are being removed in stages, with full elimination for EU tariff lines scheduled by 2027. The current preferential rate depends on the HS code and its staging category, so check TARIC for the year of import.
Conclusion
The EVFTA can remove a meaningful duty cost from Vietnamese apparel entering the EU, but only for garments that genuinely originate. For most products, that comes down to one decision: where the fabric is knitted or woven. Vietnamese, EU and Korean fabric can make a garment eligible; fabric from most other sources cannot, regardless of how much work happens in the factory.
Treat origin as part of fabric development, document it as carefully as GSM and colour, and agree the paperwork with your supplier before production. Buyers who do that turn the agreement into a real cost advantage. Buyers who leave it to the end usually find out too late that the saving was never available. If you are planning an EU or UK programme, you can browse our product range to see the categories we produce, or go straight to the contact details below.
Plan an EU Order with AT Garment Factory
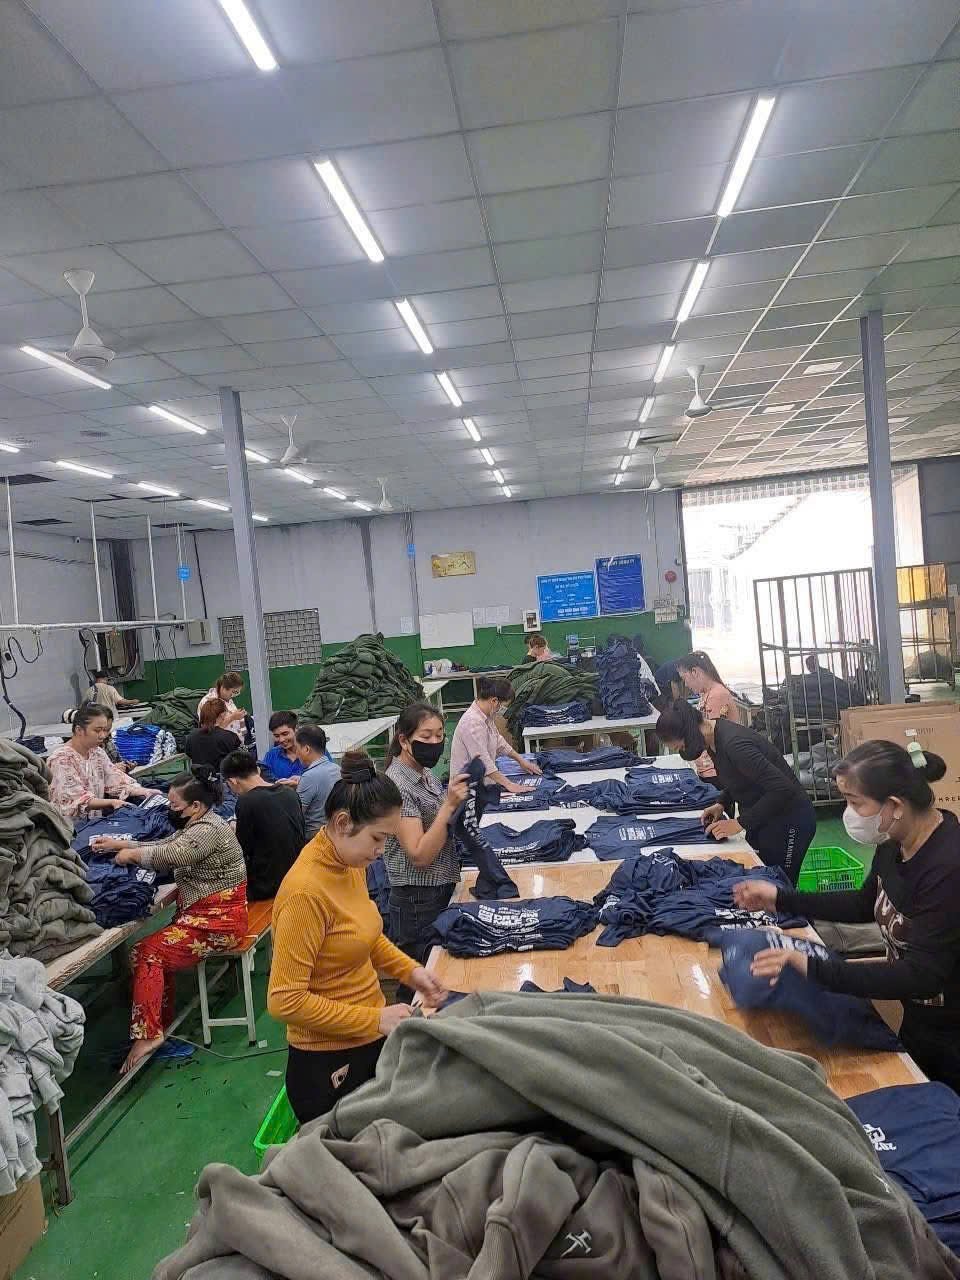
AT Garment Factory in Bình Tân, Ho Chi Minh City has more than ten years of experience in OEM, ODM and private label production, with capacity of over 100,000 pieces per month. Minimum orders start from 50 pieces for blank garments, 100 for printed orders, 200 for OEM branded production and 2,000 for hoodie, polo and uniform programmes. Send us your tech pack, target market and fabric preferences, and we can discuss fabric options with your EU or UK shipments in mind.
- Email: thanhtung113123@gmail.com
- WhatsApp: Chat with us on WhatsApp
- Zalo: Message us on Zalo
- Contact form: atgarmentfactory.com/contact